KUALA LUMPUR – The financial sector prevented approximately RM1.9 billion in attempted fraudulent transactions in the first half of 2026, surpassing the RM1.2 billion prevented throughout 2025.
Bank Negara Malaysia (BNM) Governor Datuk Seri Abdul Rasheed Ghaffour, in disclosing the matter, said more than RM37 billion worth of assets had also been recovered over the past five years.
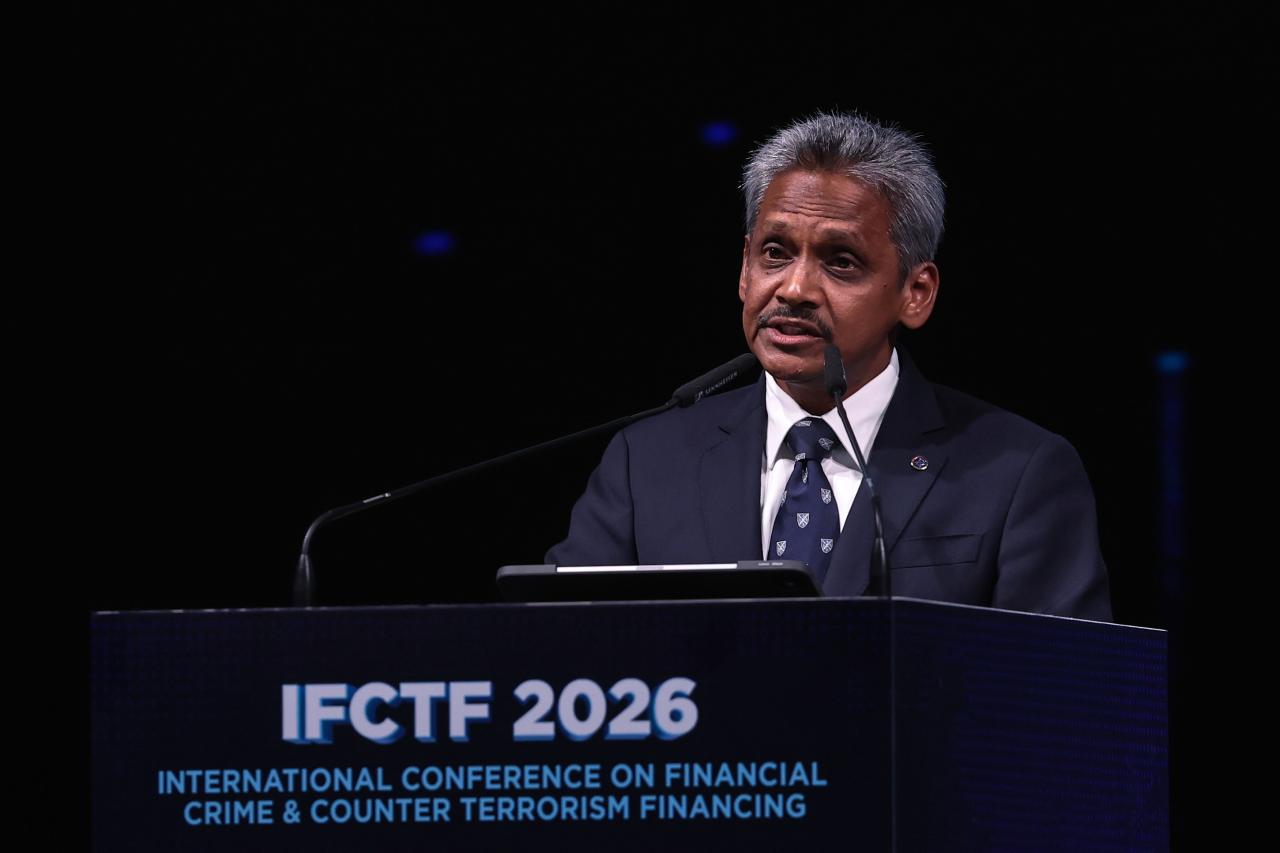
“Prominent and complex financial crime cases were also investigated and prosecuted, including those involving multiple agencies. These achievements are a testament to our whole-of-nation efforts,” he said, Bernama reported.
He said this in his speech at the International Conference on Financial Crime & Counter Terrorism Financing (IFCTF) 2026 today.
Meanwhile, Abdul Rasheed said the banking industry and PayNet would introduce an industry-wide fraud alert capability, with a pilot involving selected banks targeted for the first half of 2027.
He said the industry-wide fraud alert capability would enable banks and customers to be alerted to potential risks before transactions are completed.
“These alerts will prompt customers to pause, think and verify before proceeding with the transaction,” he said.
Abdul Rasheed said the capability could cause some disruption to customers and might also result in complaints.
“However, this is necessary to strike the right balance between offering convenience and protecting customers from fraud, particularly those who are at higher risk,” he said.
He said PayNet had identified more than 1,600 suspicious accounts, most of which were subsequently found to have associated new risks.
“This demonstrates the potential for network-level intelligence by pooling the information required by institutions to identify risks that may not be visible from the perspective of any single institution,” he said.
In support of this shift, he said BNM had strengthened the foundations of technology risk management and fraud prevention.
“The revised technology risk management policy document strengthens financial institutions’ resilience to technology-related risks, cyber risks and rapidly evolving digital crime.
“Meanwhile, financial institutions’ response to the newly issued fraud policy document further strengthens fraud risk management capabilities while encouraging the responsible use of intelligence, analytics and technology,” he said. – October 6, 2026