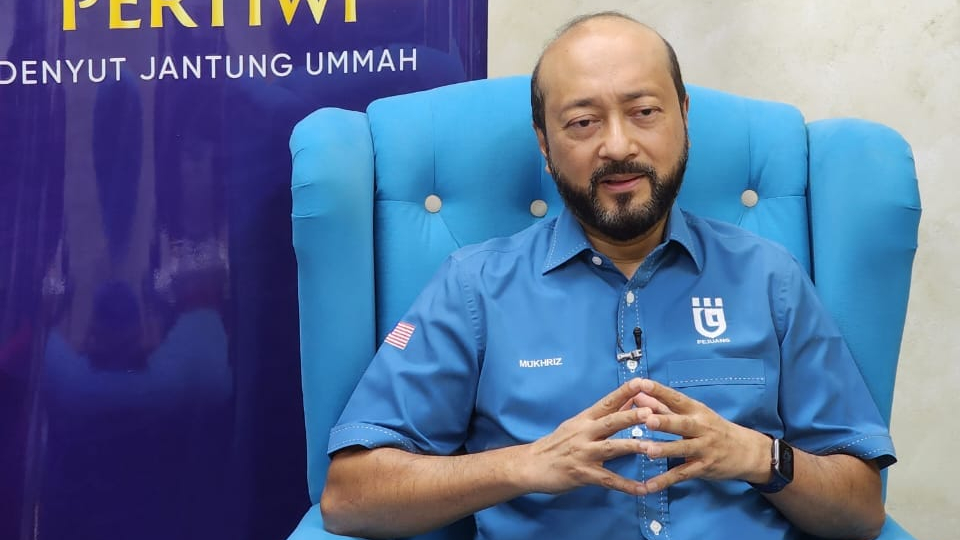
KUALA LUMPUR – Datuk Seri Mukhriz Mahathir has failed in his bid to challenge the Inland Revenue Board’s (HASiL) decision to issue additional tax assessments amounting to more than RM5 million for the 2017 to 2019 assessment years.
High Court judge Datuk Azizan Md Arshad dismissed the judicial review application today, ruling that the issues raised by Mukhriz should first be dealt with by the Special Commissioners of Income Tax (SCIT) through the appeal mechanism provided under the Income Tax Act 1967, Bernama reported.
The judge said the court agreed with HASiL that the application was an attempt to circumvent the statutory process, particularly as Mukhriz had already lodged an appeal with the SCIT under Section 99 of the Act.
“This court accepts the Inland Revenue Board’s submission that all the issues should first be ventilated before the SCIT. The issues are to be determined through the statutory appellate mechanism under the Income Tax Act 1967 (ITA). The court concludes that this application is an attempt to bypass the legally established process.
“The appellant (Mukhriz) has appealed to the SCIT under Section 99 ITA, but there are no exceptional circumstances rendering this judicial review. Therefore, the court found that this application is an abuse of the court process,” he said.
The court also ordered Mukhriz, who is Parti Pejuang Tanah Air (Pejuang) president, to pay RM5,000 in costs to HASiL, the sole remaining respondent.
On Jan 2, 2025, the High Court granted Mukhriz leave to initiate judicial review proceedings following an application filed on Dec 20, 2024.
He had initially named HASiL director-general, Finance Minister Datuk Seri Anwar Ibrahim and the Malaysian government as the first, second and third respondents.
However, on July 24, 2025, the court allowed Anwar and the government to be removed from the proceedings, leaving the HASiL director-general as the sole respondent.
In his application, the former Kedah Menteri Besar sought to quash HASiL’s decision to issue additional tax assessment notices for the 2017, 2018 and 2019 assessment years, amounting to RM5,020,707.18.
He argued that the decision was unlawful and unreasonable.
Mukhriz also sought a declaration that the penalty imposed under Section 113(2) of the Income Tax Act 1967 was null and void, and ultra vires. – November 16, 2026